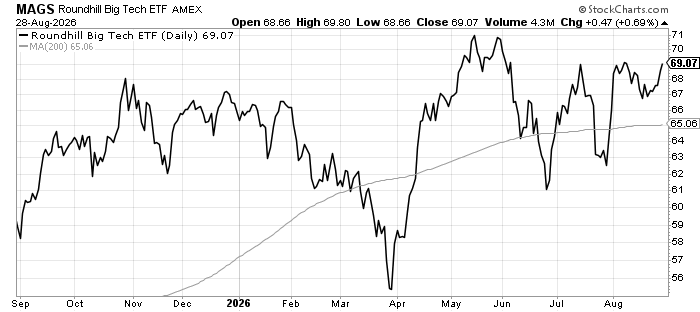
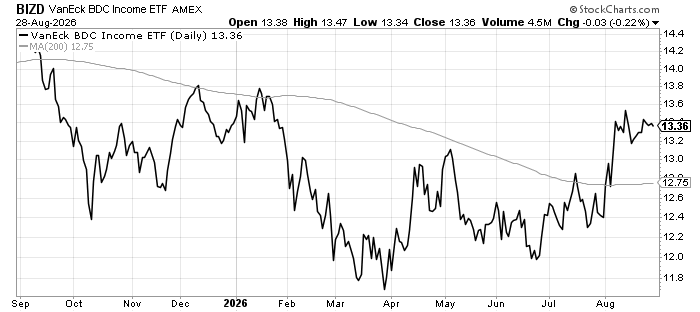
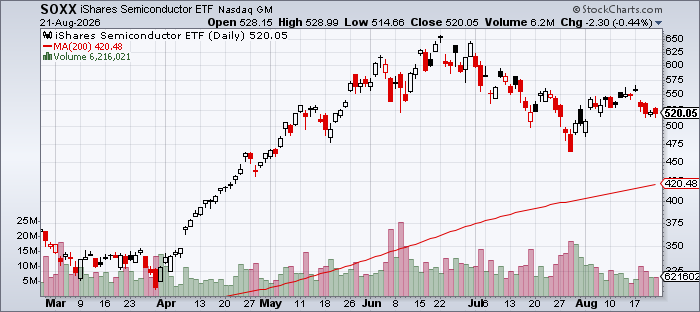
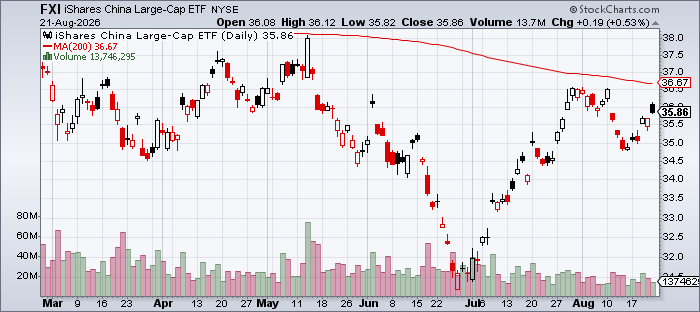
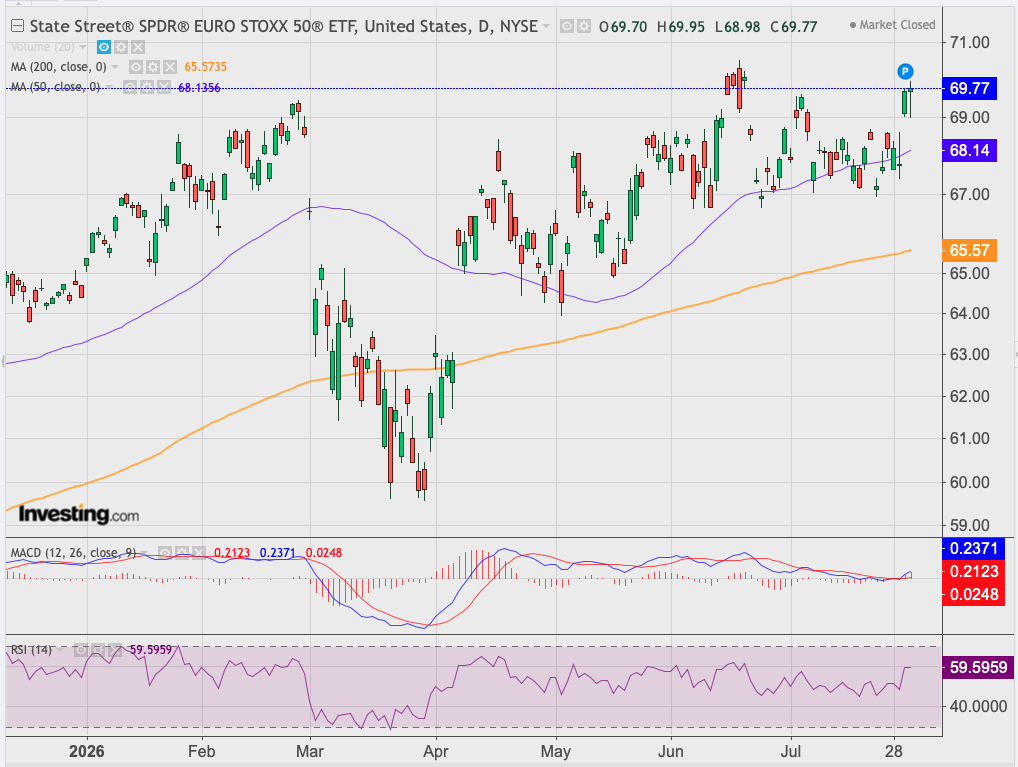
Markets were mixed rather than clearly risk-on or risk-off. US large-cap growth and semiconductors remained firm, but small caps, value stocks, Europe, Japan and much of Asia weakened, while high-yield credit was broadly flat. The message beneath the headline indices is that market leadership is narrowing and investors are becoming more selective.
TOP THEMES THIS WEEK
1. Bond yields, fiscal pressure and the return of the term premium
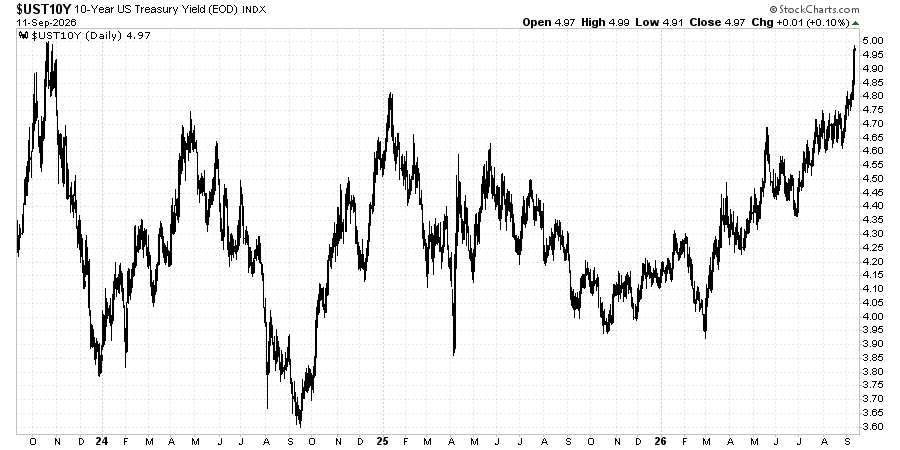
Long-term US Treasury yields remained under pressure as investors focused on persistent inflation, heavy government borrowing and greater uncertainty over the Federal Reserve’s policy approach. This matters because a rise in yields driven by fiscal risk and term premium is more damaging than one driven by stronger growth: it raises financing costs without necessarily improving corporate earnings.
2. AI spending is still booming, but the constraints are becoming more visible
Hyperscalers continue to commit extraordinary amounts of capital to AI infrastructure, while shortages are increasingly appearing in power, semiconductors, memory and data-centre capacity. Markets are still rewarding this theme — semiconductors rose 1.1% this week and remain one of the strongest areas of the equity market — but the investment story is shifting from simply owning AI beneficiaries towards identifying the physical bottlenecks that determine how quickly the buildout can continue.
3. Energy has become a renewed inflation risk
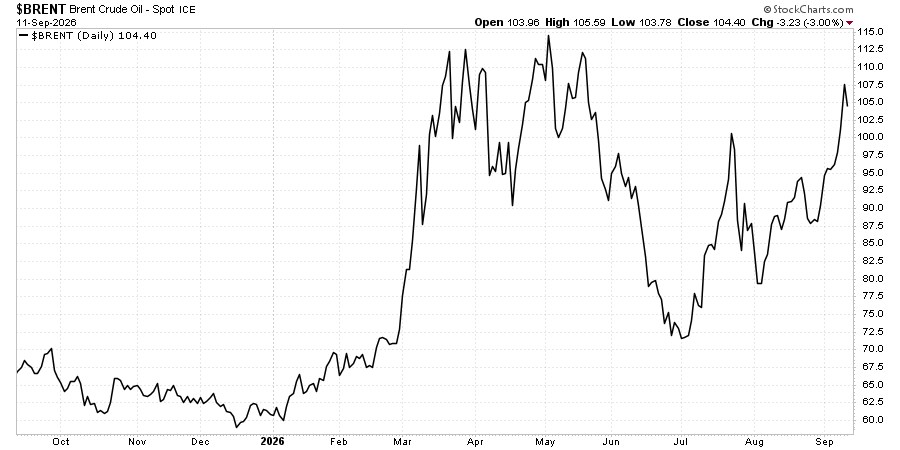
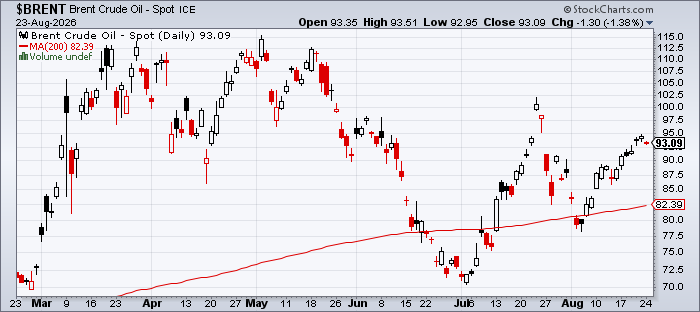
Supply disruption in the Middle East pushed crude and refined fuel prices sharply higher, with Brent still up more than 12% over the past month despite falling this week. This matters because another sustained energy shock would complicate the inflation outlook, limit the room for central banks to ease policy and place additional pressure on households and lower-margin companies.
4. Credit conditions are not breaking, but stress is becoming more uneven
Private-credit defaults have risen sharply, particularly in manufacturing and healthcare, even as some sectors such as software remain comparatively resilient. Public credit markets are not yet signalling broad stress — high-yield bonds were little changed this week — but the widening gap between stronger and weaker borrowers suggests that credit selection is becoming more important.
INVESTMENT IMPLICATIONS
The combination of narrow equity leadership, higher bond yields and rising credit dispersion argues for selectivity rather than broad risk-taking. The strongest structural opportunities remain linked to AI infrastructure and its bottlenecks, but higher financing costs make valuation and balance-sheet strength increasingly important. In fixed income, the current environment continues to favour shorter and intermediate maturities over taking large amounts of long-duration risk.
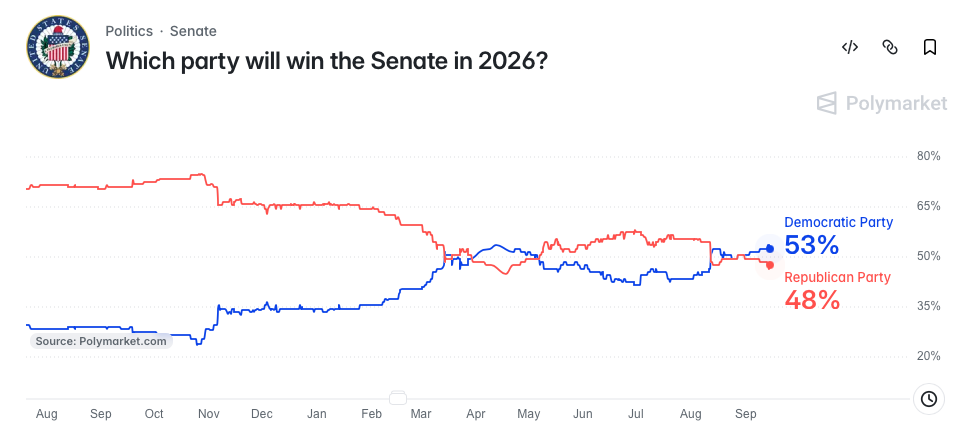
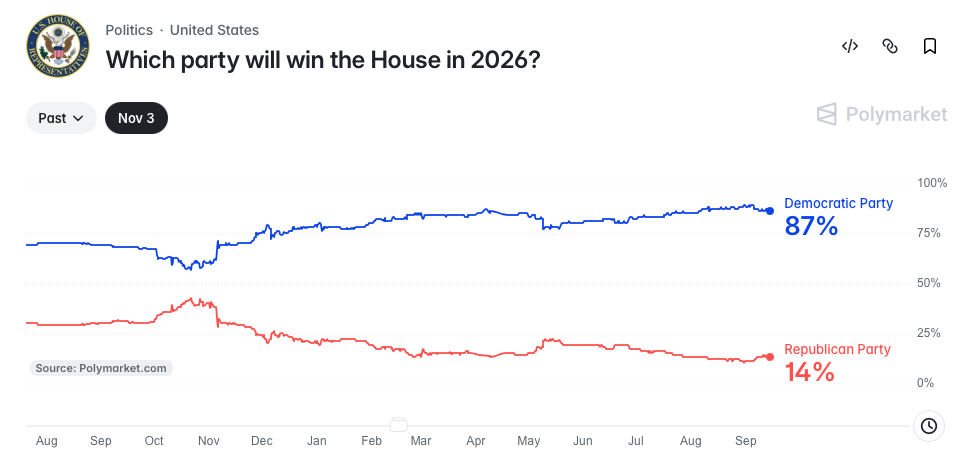
The US midterm elections on 3 November could dramatically change the balance of power in Washington. They may change much less for investors.
That sounds counter-intuitive. A Democratic takeover of Congress would severely restrict President Trump’s ability to pass legislation, while a Republican victory would preserve his control of both chambers. Yet many of the policies that have mattered most to markets during his second term — tariffs, immigration enforcement, sanctions, regulation and foreign policy — do not disappear simply because Congress changes hands.
This is the distinction investors should keep in mind before election night. The midterms are more likely to change how Trump governs than what his administration is trying to achieve.
Where the result could matter much more is fiscal policy. A Republican Congress would give Trump greater scope to spend, potentially adding to deficits and upward pressure on Treasury yields. A divided Congress would make new spending harder but increase the risk of shutdowns and debt-ceiling fights. Democratic control of both chambers would impose the strongest constraint on the administration, particularly through investigations and blocked appointments, but still leave many of Trump’s executive powers intact.
For investors, therefore, the key question is not simply whether Congress turns red or blue. It is what the election does to government borrowing, Treasury yields and eventually the cost of capital.
Republicans hold both chambers: the cleanest political outcome may not be the cleanest market outcome
If Republicans retain both the House and Senate, Trump would face the fewest political constraints.
Republicans would continue to control congressional committees, limiting the scope for hostile investigations into the administration. More importantly, control of the Senate would allow the White House to continue filling judicial, Cabinet and regulatory positions with relatively little obstruction.
It would also give Republicans their best chance of passing further fiscal measures, although narrow majorities would still limit how ambitious they could be.
This is where the investment implications become less straightforward.
A Republican victory would probably be seen initially as a continuation of the existing policy regime: more defence spending, a relatively supportive environment for conventional energy and a generally pro-business regulatory stance. That could favour defence, energy and parts of the financial sector.
But more spending would come at a time when the US fiscal position is already weak and Treasury borrowing needs are high. Continued Republican control could raise expectations of additional fiscal spending. If that translates into larger deficits and more Treasury issuance, bond investors may demand higher yields to absorb the extra supply.
So the apparently most stable political result could also be the outcome that puts the greatest upward pressure on long-term bond yields.
That matters because the problem would not stop with bonds. Higher Treasury yields raise borrowing costs across the economy and increase the discount rate investors use to value future earnings. The effect would be felt most by expensive, long-duration assets.
In short: Republican control could be positive for selected sectors while still creating a tougher backdrop for the wider market through higher yields.
Republicans hold the Senate but lose the House: less spending, more confrontation
A Democratic House with a Republican Senate would create a very different set of risks.
The most immediate change would be greater scrutiny of the administration. Democrats would control House committees and gain much more scope to hold hearings, issue subpoenas and investigate the White House, federal agencies and politically sensitive industries.
That would create more political noise, but it would not necessarily change the direction of economic policy.
The Republican-controlled Senate would still be able to confirm many Trump nominees. More importantly, the White House would retain substantial control over trade policy, sanctions, immigration enforcement, regulation and foreign policy.
What would change most is the ability to pass new legislation.
A divided Congress would make additional fiscal packages much harder. That could reduce some of the upward pressure on deficits compared with a Republican sweep. But the trade-off would be a greater risk of budget disputes, government shutdowns and eventually another fight over the debt ceiling.
A government shutdown occurs when Congress fails to approve funding for federal agencies. The debt ceiling is different: it is the legal limit on how much the government can borrow. Both can become bargaining tools when control of Washington is divided.
For markets, this matters because political gridlock can produce short bursts of volatility even when the underlying economy remains intact.
This is therefore not necessarily a bearish scenario. In fact, investors could initially welcome the reduced likelihood of additional fiscal spending if it helps contain Treasury yields. The risk is that periodic budget battles become increasingly disruptive.
The investment trade-off is fairly clear: less fiscal expansion, but more fiscal brinkmanship.
Democrats win both chambers: maximum political constraint, but limited policy reversal
A Democratic sweep would represent the biggest change in Washington, but probably a smaller change in economic policy than the headlines suggest.
Democrats would control both congressional chambers and gain significantly more power to investigate the administration. A Democratic Senate could also slow or block Trump nominees to the courts, Cabinet and regulatory agencies.
This would be the scenario where confirmation gridlock becomes a real issue.
Yet Trump would still be president.
That matters because Democrats would not be able to simply replace the administration’s economic policies with their own. Trump could veto legislation, while overriding a presidential veto requires a two-thirds majority in both chambers — something neither party is realistically likely to have.
The result would therefore be less a Democratic policy agenda than a political stalemate.
Congress could block or reshape spending proposals. It could make appointments more difficult. It could increase oversight of sectors such as financial services, private equity, digital assets, health care and energy.
But many of the White House’s most market-relevant tools would remain intact.
Tariffs can still be pursued under existing trade laws. Sanctions and foreign-policy measures remain largely under executive control. Immigration enforcement and many regulatory decisions would continue to sit with the administration.
This is why investors should be careful about describing a Democratic sweep as a wholesale reversal of the Trump agenda. It would constrain the administration, sometimes significantly, but it would not replace it.
The main market risk would again come through fiscal confrontation. With Democrats controlling Congress and Trump retaining veto power, budget negotiations could become more difficult and shutdown risks more frequent.
So although this would be the largest political change of the three scenarios, it may not produce the largest economic change.
What actually matters for investors
A Republican sweep raises the possibility of more fiscal spending and higher Treasury yields.
A split Congress reduces the chance of major new spending, but increases the risk of shutdowns and debt-ceiling battles.
A Democratic Congress creates the greatest constraint on the administration, but may leave much of Trump’s existing executive policy framework intact.
This also explains why the market reaction may not follow the political headlines.
If Republicans win and bond yields rise sharply because investors expect more borrowing, equities may struggle even though the result is viewed as pro-business.
If Democrats take Congress and Treasury yields fall because markets expect less fiscal expansion, parts of the equity market could actually benefit despite the political uncertainty.
While the election result matters, it is how bond markets react that may matter more.
It was a mixed, uneasy week. Equities staged a broad rally on Friday, but that came after a broad decline through the week, so the net picture is closer to “pause and regroup” than genuine strength. The dominant story underneath the surface is rising bond yields — the 10-year US Treasury yield closed at 4.97% on Friday 11 September — pulling credit and duration-sensitive assets lower even as headline equity indices bounced.
TOP THEMES THIS WEEK
1. AI spending is now a bond market story, not just a tech story. Big US technology firms have borrowed over $600 billion globally to fund data centre construction, and are increasingly issuing debt in Europe (sterling, euro, Swiss franc bonds) to avoid overcrowding the US market. This matters because it’s pushing up US borrowing costs to the point where large Asian technology firms (TSMC, SK Hynix) can now borrow more cheaply than US giants like Amazon and Meta — a genuine shift in who the market sees as the safer credit.
2. Government bond yields are climbing toward levels that worry equity investors. The US 10-year yield is approaching 5% and the 30-year is trading around 5.25%, and analysts increasingly expect inflation to settle nearer 3% than the 2% central banks target, due to structural pressures like ageing populations and energy costs. This matters because higher long-term yields make future company profits worth less in today’s money, which is the main channel through which rising rates eventually weigh on share prices.
3. The US-Iran conflict is keeping energy prices elevated and feeding into inflation. Fighting in the Strait of Hormuz has disrupted Qatari gas exports and pushed oil prices above $100 a barrel, and this is showing up directly in US inflation data — a hotter-than-expected August inflation reading was reported this week, with energy costs a key driver. This matters because it is one of the clearest links between a geopolitical event and the interest rate decisions markets now expect from the Federal Reserve.
4. Chinese open-source AI models are winning the adoption race on cost. Models from firms like Moonshot and DeepSeek now account for over 60% of monthly usage on the developer platform OpenRouter and over 40% of downloads on Hugging Face, with US companies including DoorDash and Airbnb adopting them to cut costs by as much as 90%. This matters because it directly challenges the assumption that US firms hold a clear lead in commercial AI, and puts pressure on the pricing power of US model providers.
WATCH THIS NEXT WEEK
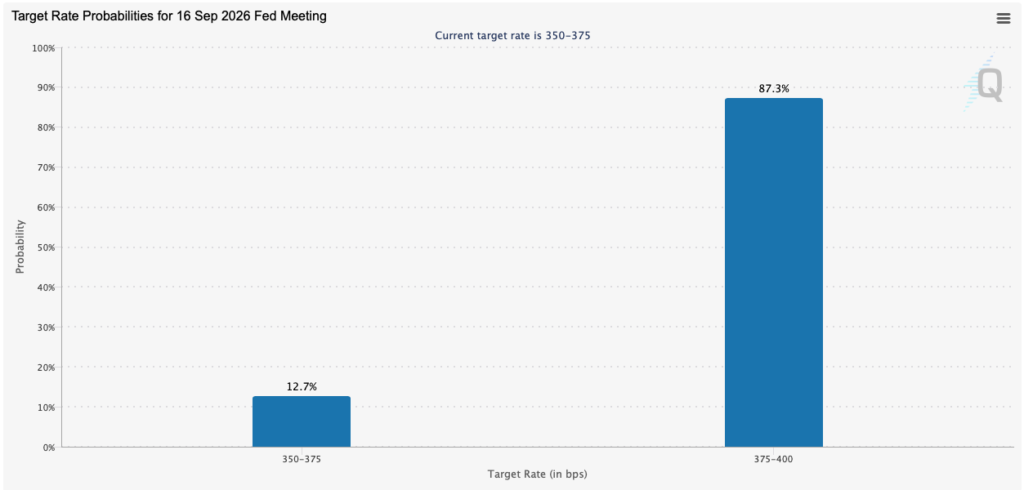
The Federal Reserve’s meeting on 15–16 September, with the rate decision due Wednesday 16 September at 2:00pm US time. This is not a routine meeting: the Fed held rates steady in July on a divided 9-3 vote, and market pricing for a rate increase (not a cut) has risen sharply since — from around 66% in late August to 87% yesterday after this week’s hot inflation data. A hike would be the first rise in this cycle, driven largely by energy-cost pressure from the Iran conflict, and would land directly on top of a bond market that is already under strain. How the Fed frames this decision — and whether it signals more increases to come — will likely set the tone for markets into October.
Equities had a broad but shallow up week — most markets rose, led by Asia, while the US barely moved. Underneath that calm surface, the signals were mixed: bonds and credit weakened, oil jumped sharply on supply disruption, and gold’s rally paused. This was not a clean risk-on week. Equities behaved as if conditions were improving; credit and long-dated bonds behaved as if they were not.
TOP THEMES THIS WEEK
1. The AI spending boom is cracking the “momentum trade.” The largest tech firms are pouring more than $700 billion into AI infrastructure, but the basket of high-flying AI-linked stocks (Nvidia, AMD, Micron and similar names) has fallen roughly 9% since July while the broader market has gained. This matters because it signals investors are starting to separate genuine AI winners from speculative momentum — a stock-picker’s market is replacing a “buy anything AI” market, and heavily-leveraged, high-capex tech names are now more exposed to rising interest rates than before.
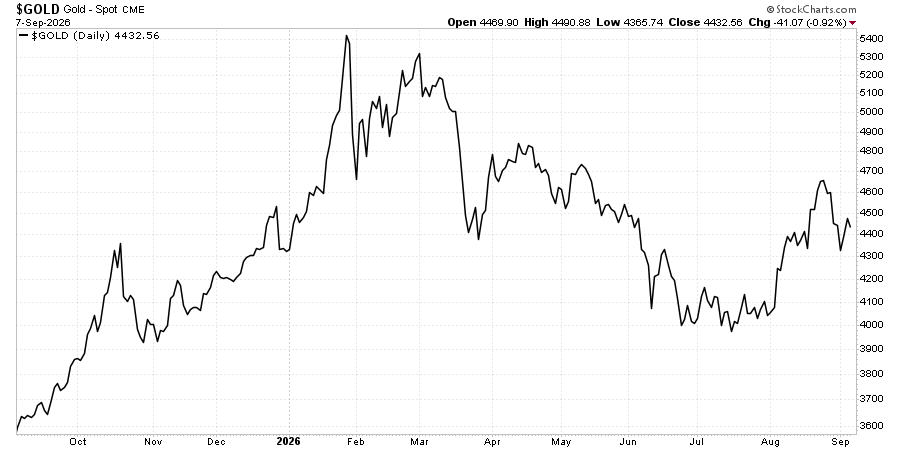
2. Bond yields are climbing on fiscal and inflation concerns, reviving the “debasement trade.” US government debt has crossed $40 trillion, the new Fed Chair has signalled a willingness to keep policy tight, and this pushed investors into gold, Bitcoin and emerging-market bonds as a hedge against a weakening dollar — though a hawkish Fed speech on Friday pulled the US 10-year yield back up and took some steam out of gold. This matters because it shows fiscal strain is now a genuine market driver, not background noise, and that the safe-haven trade can reverse quickly on a single policy signal — consistent with gold’s own pullback this week (down close to 1% on the week after a strong month).
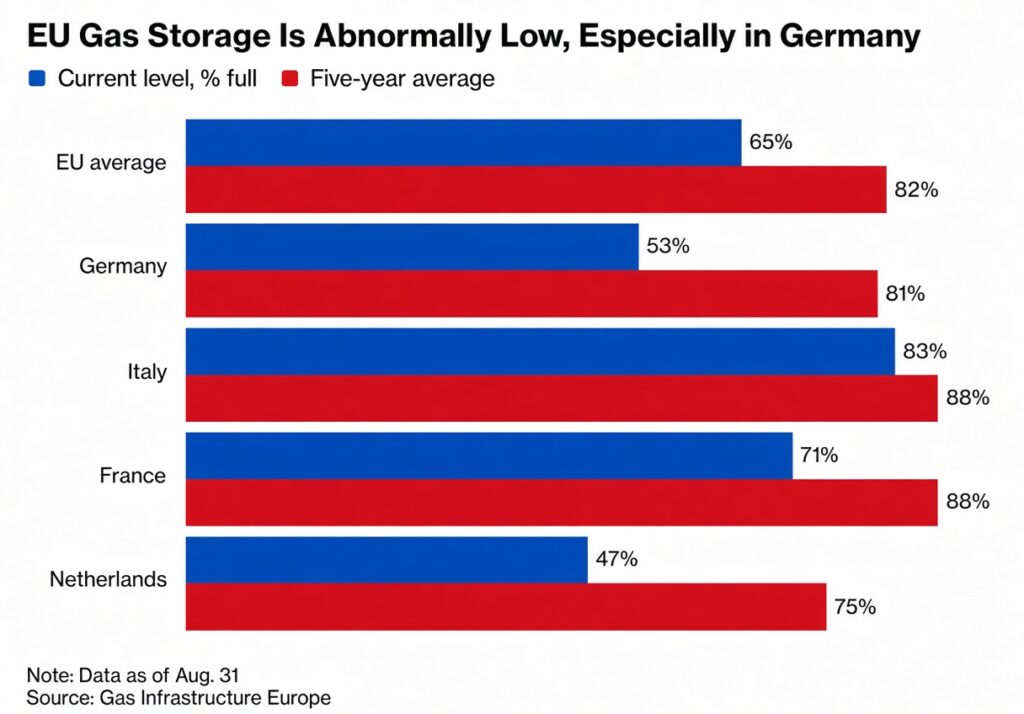
3. An energy crunch is building into winter. War-related disruption in Iran and Ukrainian strikes on Russian refineries have driven a spike in oil and diesel prices, while Europe heads into winter with unusually low gas storage levels. This matters because it raises the risk of a European energy price shock this winter, with knock-on effects for inflation and central bank policy — and it lines up directly with this week’s price action, where oil rose more than 7% and natural gas remains up nearly 30% on the month.
4. Private credit is showing its first real cracks. Redemption requests have forced several private credit funds in Australia and the US — including large, well-known names — to cap withdrawals after investors tried to pull far more capital than the funds could return. This matters because private credit has grown enormously as a lightly-regulated lending channel and has never been tested under stress; these caps are an early signal of that stress arriving, and they help explain why credit markets are underperforming equities this week rather than confirming the rally.
WATCH THIS NEXT WEEK
The gap between equities and credit. This week, most equity markets rose while both high-yield and investment-grade corporate bonds fell — a genuine divergence, since credit usually strengthens alongside equities in a real risk-on move. The private credit redemption caps give a plausible reason why: money is quietly becoming more cautious about credit risk even as stock prices stay firm. If credit keeps weakening while equities keep rising, that gap normally closes with equities catching down, not credit catching up. Watch high-yield bond prices closely next week — they are the more honest signal right now.
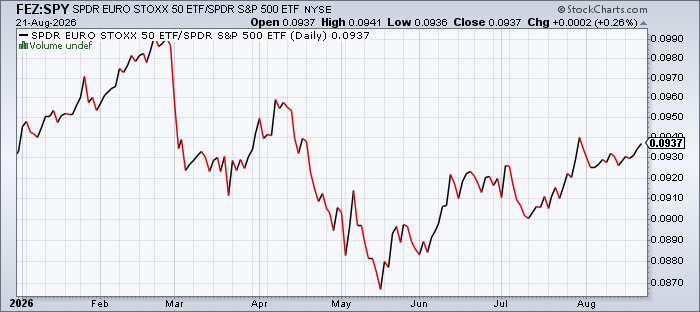
Markets were mixed rather than clearly risk-on or risk-off. The S&P 500 and Nasdaq edged higher, but breadth weakened as semiconductors, small caps, Europe and China lagged, while long-dated US Treasuries and the dollar strengthened. Credit remained calm, suggesting caution and rotation rather than a broad retreat from risk.
TOP THEMES THIS WEEK
1. AI is shifting from a growth story to a financing and returns story. The cost of using AI continues to fall, but the cost of building the infrastructure is rising, while hyperscalers are issuing large amounts of debt and investors are beginning to question when the spending will generate meaningful returns. This matters because the market is increasingly likely to differentiate between companies that simply spend heavily on AI and those that can convert that spending into durable profits.
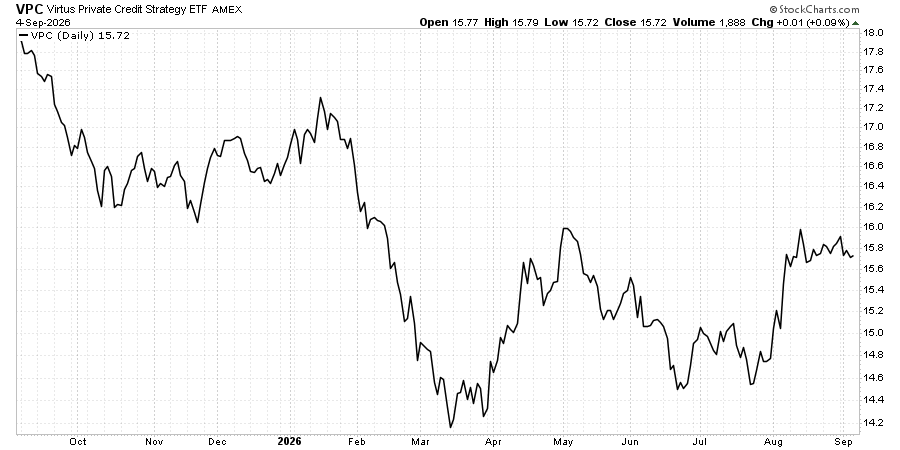
2. Private equity’s liquidity problem is becoming harder to hide. Buyout firms are increasingly using structured equity, dividend recaps and other financing arrangements to return cash to investors because conventional exits remain difficult and holding periods have stretched. These structures provide near-term liquidity, but they may also defer rather than solve the underlying valuation and exit problem, raising questions over the quality of reported distributions. Private credit ETF tracker has broken out of its 20dMA, providing some relief for the time being.
3. European banks are transferring more credit risk to insurers. Banks are making greater use of synthetic risk-transfer structures to reduce the capital tied up against their loan books, including arrangements where insurers promise to absorb losses without fully funding that commitment upfront. The transactions can improve bank capital efficiency, but they also create additional links between banks and insurers that could amplify stress if corporate defaults rise materially.
4. Geopolitical pressure is increasingly being applied through energy and financial channels. Saudi Arabia is adapting its oil export routes to ongoing regional disruption, while the US is exploring more aggressive legal mechanisms to seize and sell Iranian oil cargoes. The immediate market effect has been contained, with Brent actually falling this week, but the broader risk is that economic pressure on Iran increasingly shifts towards shipping, sanctions enforcement and third-country financial institutions.
Risk appetite weakened this week, led by a sharp sell-off in semiconductors and other previous growth leaders. The S&P 500 fell 1.4%, the Nasdaq 2.4% and semiconductors 5.5%, while value stocks, emerging markets and China were more resilient. The cross-asset message was not a conventional recession scare: oil and gold rose sharply while the dollar weakened, pointing instead to a mixture of geopolitical risk, US fiscal concerns and profit-taking in expensive market leaders.
TOP THEMES THIS WEEK
1. AI spending is becoming a financial risk, not just a growth story
The scale and complexity of AI investment is becoming harder to ignore, with large technology companies taking on substantial lease commitments, long-term purchase obligations and indirect financial backstops that may not be obvious from headline debt or capital expenditure figures.
This matters because investors are increasingly likely to judge the AI cycle on returns rather than spending. The sharp 5.5% fall in semiconductors this week may therefore be important: after an extraordinary run, the market may be becoming less willing to reward ever-higher AI expenditure unless it produces corresponding revenue, margins and cash flow.
2. China remains economically weak, but its equity market is behaving better
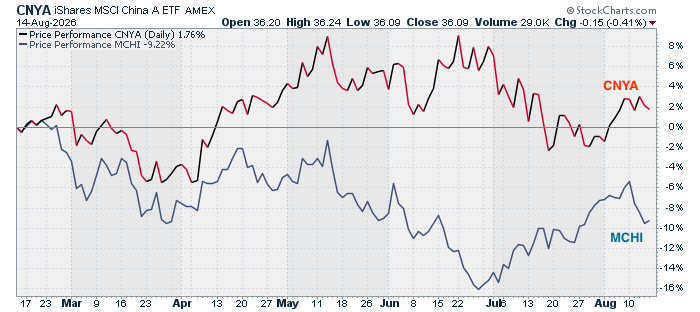
China’s July data pointed to continuing weakness in consumption, industrial activity and especially property, with falling home prices and deeply depressed property investment. Policymakers still appear to favour targeted credit support and subsidies rather than the large-scale fiscal stimulus investors have repeatedly hoped for.
Yet Chinese equities rose 1.9% this week while most developed markets declined. That divergence deserves attention. It suggests that considerable economic pessimism may already be reflected in Chinese asset prices, although improving market performance should not yet be mistaken for evidence that the underlying economy has turned.
3. The campaign against Iran is becoming an economic and market risk
US pressure on Iran is shifting towards economic isolation, with efforts to constrain oil exports, financial links and regional trading channels. The main complication remains China, which continues to provide an important market for Iranian oil and could retaliate if major Chinese companies or financial institutions are targeted.
Oil’s 6.1% rise this week, together with a 5.1% gain in gold, suggests markets are taking this risk increasingly seriously. A further escalation could keep energy prices elevated and complicate the inflation outlook, even if global economic growth softens.
4. Europe and Japan continue to offer a credible alternative to US market concentration
European earnings have been stronger than expected, while Japanese corporate profitability is broadening beyond exporters and technology companies towards domestically focused businesses. Both markets therefore have earnings support that is less dependent on the AI capital-spending cycle dominating the US.
The price action was more nuanced this week: Europe fell only 0.5%, but Japan dropped 3.1%. Even so, the underlying earnings picture strengthens the case for maintaining regional diversification rather than relying excessively on US technology leadership.
Financials continue to confirm the bull market, but the confirmation is no longer unequivocal. The sector’s fundamental foundation has strengthened: C&I lending is growing about 8% year over year, major-bank loan books expanded broadly, net interest income improved, capital-markets revenues accelerated, and credit losses remained contained. Regional banks have recently outperformed diversified financials—an important improvement because the rally is no longer confined to money-center banks.
The yield curve has steepened, with 2Y–10Y near +45 bp and 3M–10Y around +90 bp. However, this is principally a long-end, inflation/fiscal-risk steepening, not an unambiguously benign growth signal. It supports bank margins but raises mortgage, CRE-refinancing and valuation risk.
The thesis has strengthened modestly, chiefly because credit creation and earnings breadth improved. Offsetting this, the April SLOOS still showed modest C&I tightening, speculative-grade spreads are unusually compressed, and office/multifamily CMBS stress remains severe. Financial markets are pricing a cleaner outcome than bank-lending and property data justify.Over 3–6 months, the principal risks are renewed inflation and higher long yields, abrupt HY spread normalization, weakening consumer credit, a CRE refinancing accident, and geopolitical or trade shocks. Portfolio implication: remain overweight high-quality diversified banks, insurers and exchanges; use more caution in leveraged regional banks, lower-quality credit and long-duration equities.
Markets were moderately risk-on: 11 of the 12 equity markets tracked rose, credit gained modestly and the dollar weakened. The rally was broad but uneven, led by South Korea and semiconductors, while China fell sharply; stronger gold, energy and weak long-dated US Treasuries added an inflation-sensitive undertone.
TOP THEMES THIS WEEK
AI investment is becoming a credit story
Nvidia and major financial institutions are developing a financing pipeline of up to $500 billion for AI infrastructure, while chipmakers are increasingly supporting loans secured against their products. This expands the AI build-out but introduces contingent liabilities and collateral risks that may only become visible when demand slows or technology becomes obsolete.
AI market concentration is increasing volatility
Leveraged funds have channelled growing amounts of capital into a small group of AI-related companies, particularly South Korean memory-chip producers, even as investors question whether the memory cycle is approaching a peak. The week’s strong gains in South Korea and semiconductors show that the trade retains momentum, but crowded positioning could amplify any reversal.
China is mobilising capital while managing domestic risks
Beijing is accelerating technology listings and providing strategic industries with comparatively cheap funding, while investors rotate from infrastructure names towards profitable internet platforms. At the same time, uncertainty over expiring commercial-property land leases remains a systemic concern; the 4.04% weekly fall in Chinese equities suggests that these risks are outweighing the broader rally for now. However, the mainland focused market remains well supported, falling 0.98% for the week.
Credit strains are emerging beneath stable public markets
Defaults and borrower watchlists at major private-credit funds have risen to their highest levels in several years, despite relatively calm public credit markets this week. This divergence matters because private credit may be giving an earlier warning about weakening corporate balance sheets, particularly among highly leveraged software companies exposed to AI disruption.
Global equities rose broadly, led by semiconductors, South Korea, US technology and Japan, while the dollar weakened and bonds made modest gains. The mood was risk-on, but the sharp rise in gold and steep fall in energy prices showed that investors remained cautious about geopolitical risk, inflation and growth.
The global AI race intensified
Chinese AI developers continued to narrow the performance gap with leading US models while competing aggressively on cost, and SK Hynix announced substantial investment in additional memory-chip capacity. This strengthens the long-term case for AI infrastructure but increases pressure on software providers and model developers that lack either technical leadership or a clear cost advantage.
The Strait of Hormuz remained a major source of energy uncertainty
Iran and Oman explored a deal to reopen the Strait, but Iran’s proposed restrictions on US and Israeli vessels complicated negotiations and reports of further naval action kept geopolitical risk elevated. Despite these concerns, Brent fell 8.78% and gasoline 12.83% during the week, suggesting that markets placed more weight on possible de-escalation and weaker future demand than on immediate supply disruption.
Inflation concerns complicated the outlook for monetary policy
Three Federal Reserve officials favoured higher interest rates, citing persistent inflation pressures from tariffs, war and AI-related investment, while the US and Japan intervened jointly to support the yen. The combination matters because intervention may loosen US financial conditions even as parts of the Federal Reserve argue that policy should become tighter, making the path for interest rates and currencies less predictable.
Financial vulnerabilities became more visible
Japanese life insurers reported large unrealised bond losses, Blackstone marked down assets in a private-credit fund, and high retail borrowing against shares highlighted the amount of leverage behind the market. These pressures have not yet caused broad market stress, but they could amplify losses if interest rates remain high or enthusiasm for AI-related assets weakens abruptly.
INVESTMENT IMPLICATIONS
Broad equity participation supports maintaining exposure to risk assets, particularly where earnings and balance sheets can withstand higher interest rates. However, weak energy prices and emerging credit concerns argue against taking excessive risk.
Markets were cautiously risk-on, with most equity markets advancing and China and Europe leading. The rally was uneven, however: semiconductors and South Korea fell sharply, energy prices weakened and gold rose, pointing to continued concern beneath the positive headline performance.
TOP THEMES THIS WEEK
AI financing raises questions about the quality of demand
Nvidia is pursuing financing arrangements reportedly exceeding $750 billion to accelerate investment in AI infrastructure. The scale supports continued spending across the AI supply chain, but concerns about circular financing raise the risk that reported demand is being amplified by suppliers funding their own customers.
Chinese competition challenges the semiconductor equipment industry
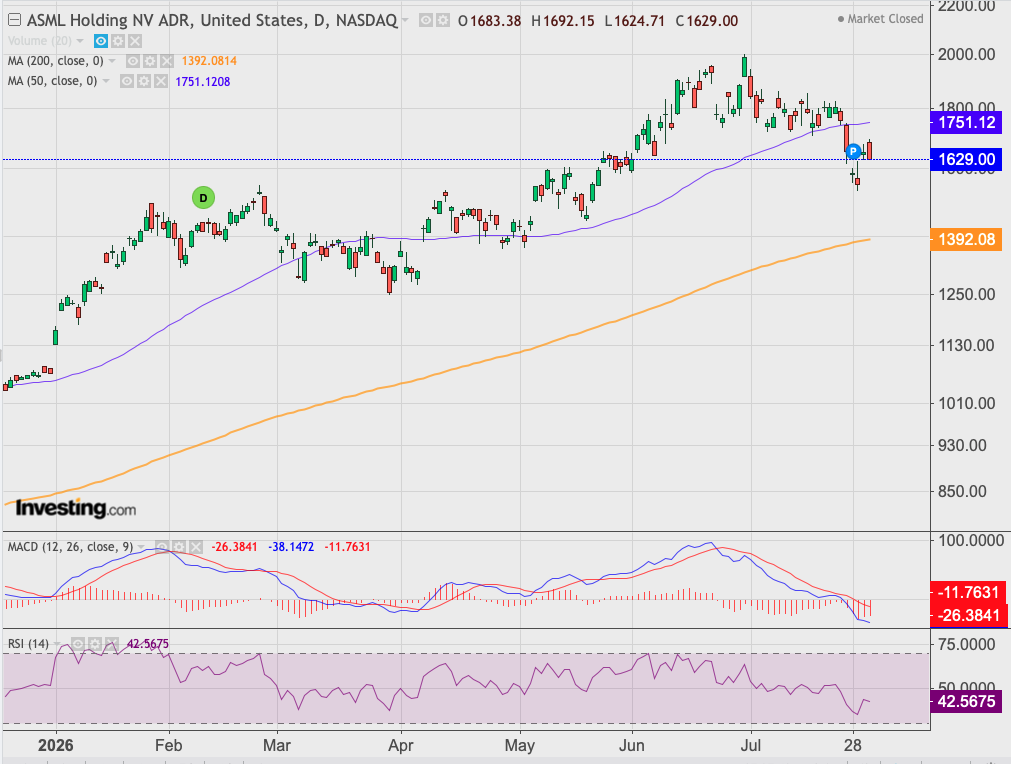
ASML shares fell after reports that Chinese companies had begun mass-producing specialised chipmaking equipment. This matters because faster Chinese localisation could weaken the long-term pricing power and market access of established Western suppliers while accelerating the development of a more separate Chinese semiconductor supply chain.
Companies are reassessing AI’s effect on employment
Several large US companies have resumed hiring after finding that AI systems still require skilled employees to implement, supervise and use them effectively. This suggests that AI adoption may change the composition of employment more quickly than it reduces total headcount, increasing the value of specialised technical and operational talent.
Equity leadership shifted away from semiconductors
China, Europe and most major equity markets rose, while semiconductors declined 4.20% and South Korea fell 3.60%. The divergence matters because it suggests that investors are rotating geographically and across sectors rather than expressing broad confidence in global growth or the established technology leadership.
WATCH THIS NEXT WEEK
Semiconductors. Their 4.20% weekly decline and 10.85% monthly fall contrast with gains in the S&P 500, Nasdaq and global equities. It is a rotation for now until weakness is seen in non-semi sectors.
INVESTMENT IMPLICATIONS
The combination of positive equity breadth, a weaker dollar and stable credit supports measured risk exposure, but the weakness in semiconductors, and Korea bears watching.